RBI Monetary Policy Review: Beginning of a shallow tightening cycle
By Prerna Singhavi, EPR, NSE
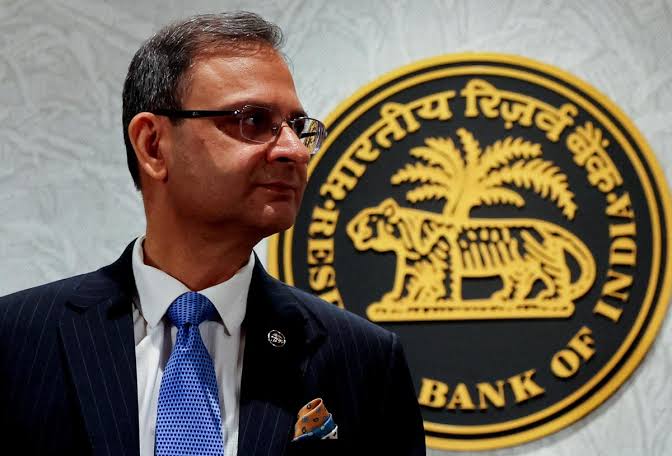
 In line with market expectations, the RBI’s Monetary Policy Committee (MPC) unanimously raised the repo rate by 25bps to 5.5% and shifted the stance to “calibrated tightening”, marking the first rate hike since February 2023. The policy tone was relatively hawkish, reflecting a less favourable growth-inflation balance and a clear reassessment of the inflation trajectory. The FY27 CPI inflation forecast was revised up by 20bps to 5.2%, with inflation expected to average at around 5.8% over the next three quarters. Core inflation is projected at 4.4%, indicating some broadening in underlying price pressures, although inflation remains predominantly supply-driven, with limited evidence so far of sustained demand-side pressures. At the same time, the FY27 GDP growth forecast was revised up by 40bps to 7.1%, supported by resilient private consumption, investment, manufacturing, services and exports. This resilience gives the RBI greater room to prioritise inflation containment without materially compromising growth at this stage.
The October action is likely to mark the beginning of a calibrated tightening cycle. With the policy rate at 5.5% and inflation projected to remain elevated over the coming quarters, the ex-ante real policy rate is likely to stay mildly negative initially. Further calibrated hikes could move real rates modestly into positive territory, although monetary conditions may still remain short of becoming significantly restrictive. Rate cuts therefore are unlikely in the near term, leaving the policy choice between a pause and further tightening. The terminal rate will depend on the persistence and breadth of inflation, the emergence of second-round effects and the degree to which higher rates begin to weigh on activity. Sizeable surplus liquidity remains an additional complication, as weaker transmission could dilute the intended tightening impulse, making active liquidity management imperative.